By Mark Keenan
November 13, 2026
Introduction
Nearly two decades after the global financial crisis of 2008, the relationship between private banking, public debt and financial power remains a subject of considerable importance.
Recent figures from Ireland's Comptroller and Auditor General demonstrate the continuing financial consequences of the banking crisis. In September 2026, the watchdog reported that the net cost of the Irish banking bailout, excluding interest, was approximately €42 billion, while interest attributable to the bailout amounted to €650 million in 2025.
These findings raise enduring questions about the structure of modern banking, the creation of credit, and the allocation of financial risks between private institutions and the public.
There are systemic aspects about the banking, monetary, and economic system that are not taught in the schools and universities of the world and are rarely discussed on corporate owned news and media networks. Knowledge of these aspects is essential for anyone that wishes to understand how the economic world 'actually' works and how worldwide society is subject to the debt-money system (currently almost all governments of the world are in vast debt) while the vast resources of human productivity and of nature are continually exploited by a small group of people that control these systems. See also my book Demonic Economics and the Tricks of the Bankers.
This article explores:
- Why do governments prioritise GDP Growth?
- The treadmill of usury, tax and debt slavery
- The debt-money system increases and reduces the availability credit at will
- The boom-bust-bailout Cycle that places nations in debt
- The 2008 banking crises in Europe and the Icelandic solution
Why Do Governments Prioritise GDP Growth?
Without GDP growth the (privately owned) debt-money banking system fails. The real reason governments prioritise GDP growth is so that sufficient tax monies can be collected so that interest can be paid to the international banking system. Governments often maintain that the ultimate purpose of economic GDP growth is in fact to improve wellbeing. This is not in fact so. John Jopling (RIP) of the Foundation for the Economics of Sustainability wrote in 2003:
"The real reason why governments regard growth as desirable is that, with a debt-based money system, if the economy does not grow, it collapses. This is something all politicians are naturally and rightly extremely keen to avoid. Growth is an absolute imperative imposed on governments by the nature of the current money system. Thus, it is in the nature of the money system, not the choice of government, that growth must be maintained." i
Governments are buried under the lie. It is rarely acknowledged by politicians that the main reason for the constant drive for GDP growth is to pay interest to the banking system. The way in which the global economic system is designed automatically ensures that the economy operates in such a way that wealth flows to private banks, the economy is unstable, and the economy is blind to the limits of natural resources or the need for humanity to live in symbiosis with the natural world.
A government prioritises growth, yet whether it is 'good' growth or 'bad' growth is not the focus (good growth would not impact on environmental and social resilience.) The pseudo-science of neo-classical economics proposes that increased GDP growth can reduce pollution in what is called the environmental Kuznets curve (EKC). However, this EKC argument is false. The EKC posits that pollution increases with economic growth in the early stages of development and that beyond a certain level of development the trend reverses, and economic growth improves environmental conditions by creating the resources to do so. However, the EKC has never been validated.
And the public are not generally aware that the need for GDP growth is imposed by the debt-money system controlled by private banks nor that the creation of debt money by private banks is unnecessary and is against the public interest (because governments could create and issue debt-free money themselves as has been done in the past). "It is well enough that people of the nation do not understand our banking and monetary system," said Henry Ford, "for if they did, there would be a revolution before tomorrow morning."
Commercial Banks Create Debt-Money Through Lending
The fact that commercial banks create debt-money through lending is not merely a theory advanced by monetary reformers. It has been explicitly acknowledged by the Bank of England, which explains that when commercial banks extend loans, they create corresponding deposits that function as money in the wider economy. As John Scales Avery, professor at the University of Copenhagen, wrote:
"Under the system of fractional reserve banking, profits from any expansion of the money supply go to private banks rather than being used by governments to provide social services. This is basically fraudulent and unjust; the banks are in effect issuing their own counterfeit money."
In 1944, Italian author Ezra Pound, described how the US fell into the hands of the international usurocracy during the civil war after 1863. He states:
"The basic fact of the history of the U.S.A. is the suppression of the colonial paper-money... the bank hath benefit of the interest on all moneys which it creates out of nothing... The purpose of a monopoly is to be able to sell the material or product monopolized at an unjustly inflated price, scorning the public good and victimizing one's neighbour... The monopoly of money, or the restriction of its circulation, is merely a variation of this simple form of monopoly... And it is to this that Jefferson alludes in the phrase:"No one has a natural right to be money-lender save him who has it to lend."
"The... bankers rule the world through debt, which is money they create out of nothing. They need world government to ensure no country defaults or tries to overthrow them. As long as private bankers, instead of governments, create money the human race is doomed. These bankers and their allies have bought everything and everyone." - Henry Makow, Author
This raises important questions about the allocation of monetary power, the relationship between private credit creation and public policy, and the extent to which societies should depend upon commercially issued debt as a principal source of money.
The Treadmill of Usury, Tax and Debt Slavery
When you get a mortgage, loan, or a credit card, the debt money is created out of thin air when you sign on the dotted line of the contract, yet you will have to work (maybe for years) to generate the money to pay back the bank plus interest - in essence, this is a subtle form of slavery as the bank never had the money in the first place.
Then there is also the national debt. Income tax monies collected by governments from the people is one of the methods used to service the debt governments owe to the international finance system, money that was also originally created entirely from nothing by privately-owned mega-banks.
"Federal income tax was instituted specifically to coerce taxpayers to pay the interest due to the banks on the federal debt. If the money supply had been created by the government rather than borrowed from the banks that created it, the income tax would have been unnecessary.... There is a way out of this morass. The early American colonists found it and so did Abraham Lincoln and some other national leaders: the government can take back the money-issuing power from the banks. "- Ellen Brown, Author of the book 'The Web of Debt'
"Between usury and taxes the consumer is really played for a sucker. God's law permits no property tax for it is discriminatory... It discourages stability and brings about a shifting, irresponsible citizenry with no ties to the land. Under our present system, accident, sickness, or old age easily dispossesses a man of his home but in no way reduces his expense...."- Dr. Franklin Snook, Author of America Needs the Divine Law
Most governments of world are debtors and servants to the lender bankers, not to the people. Yet some researchers claim that the people, the men and women are the real lenders (grantors of credit) but we are not recognised as such. Why?
The Debt-money System Increases and Reduces the Availability Credit at Will
Decades of vastly excessive consumerism has been required to keep the system from derailing. The debt-money system increases and reduces the availability credit seemingly at will often creating 'boom, bust and bailout' cycles - this means that the economic system is unstable by nature. It involves cycles of credit expansion and contraction, which can contribute to financial instability, asset-price bubbles, recessions and, in severe cases, government-funded banking bailouts. Commercial banks play a central role in creating credit through lending, while central bank interest-rate policies, financial regulation, market conditions and institutional incentives influence the expansion and contraction of credit. These arrangements can encourage excessive risk-taking during periods of economic growth, while the consequences of financial collapse may, and often do, ultimately fall upon taxpayers.
If sufficient loans are not repaid to a commercial bank it will become insolvent. This has happened in many countries, for example in various countries in Europe during the banking crisis of 2008.
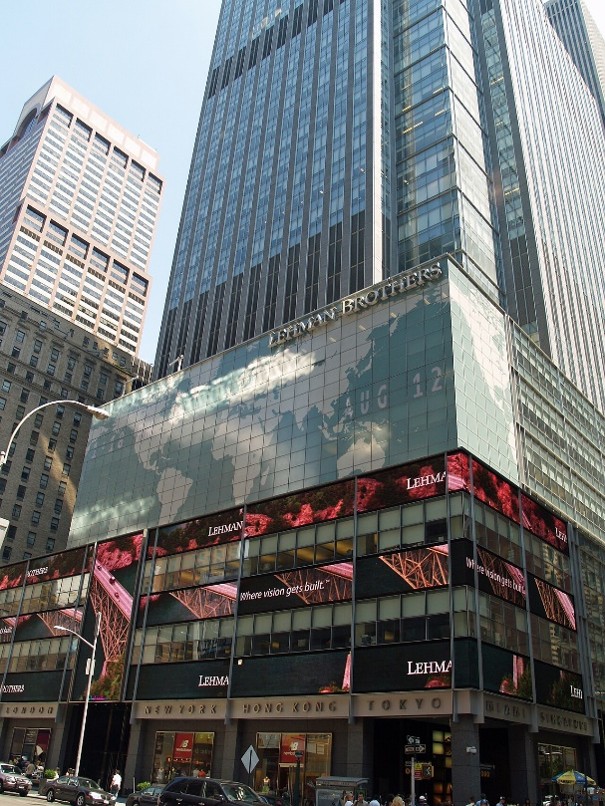
The collapse of Lehman Brothers (headquarters pictured), the fourth-largest U.S. investment bank, on September 15, 2008, is often considered the climax of the 2008 financial crisis. (Licensed under CC BY-SA 3.0)
[Aside: Bear in mind that these private banks never held the original monies in the first place, and, the cruel bait and switch is that it is actually the people that are the grantors of credit when they sign a mortgage or loan (a promise to pay), however, the bank typically never pays back the grantor of the credit. Including interest one typically pays the bank about twice the amount of the loan or mortgage. Yet, the bank does not pay equity for that promissory note, and presumes that we have abandoned our securities].
Typically a national government then intervenes to bail out those commercial banks, being under pressure to do so from the international banking system. Critics claim that by controlling the availability of credit the private banking system intentionally orchestrates boom-bust-bailout cycles, at will, which places nations in further debt.
When major commercial banks face insolvency, governments may intervene through guarantees, recapitalisation, emergency support or other rescue measures in an effort to prevent wider financial collapse. Such interventions can transfer substantial financial risks and losses from private institutions to the public sector.
This creates a fundamental problem of moral hazard: financial institutions may benefit from profits during periods of economic expansion while anticipating government intervention if their failure threatens the wider financial system. The resulting arrangement can encourage excessive risk-taking, particularly where financial institutions are considered too systemically important to fail.
The Irish banking crisis of 2008 provides a striking example of how excessive private lending, inadequate regulation and government intervention can leave taxpayers bearing significant costs. The European Central Bank (ECB) exerted pressure on the Irish government to bail out private banks and unsecured bondholders in 2010. In 2012 RTE, Ireland's National Television Service reported that the ECB informed an Irish Government Minister that "a bomb will go off in Dublin"if Anglo bondholders are not paid.
"He [Minister for Transport and Tourism, Leo Varadkar] said that the Troika told the Government that "we don't want you to default on these payments, it is your decision ultimately but a bomb will go off; and the bomb will go off in Dublin and not in Frankfurt." - RTE television reporting Minister Varadkar's comments 22nd January 2012. [Note: The Troika is a term used to describe the European Commission (EC), the European Central Bank (ECB) and the International Monetary Fund (IMF).]
Furthermore, a letter was sent by the ECB to pressure the Irish Government to accept a bailout. In that letter then ECB head Jean-Claude Trichet told Ireland in November 2010 that it would not extend further emergency funding to the country's banks if Dublin did not sign up to a bailout, according to the letter which was finally released after years of lobbying.
The so-called crises of 2008 represented an opportunity for a re-evaluation of the values that our banking system and economic system are based on. Alas, this opportunity was spurned, and almost all governments bailed out the banks. This resulted in increased taxes, national austerity measures and/or the privatisation of national assets due to conditionalities on credit.
For example, Ireland incurred enormous costs servicing its national debt - a significant portion of this debt (€85 billion) was incurred due to bailing out private commercial banks in Ireland in 2008 ii. The annual interest payments alone are, in effect, a seemingly never-ending shackle of debt servitude and a form of slavery for the tax payers in Ireland. Similar bailout situations have occurred in many other countries worldwide.
According to Ireland's National Treasury Management Agency (NTMA), annual government debt-interest expenditure reached approximately €7.7 billion in 2013 and remained above €6 billion annually between 2012 and 2016. Although borrowing costs subsequently declined, Ireland's gross general government debt still stood at approximately €209.9 billion at the end of 2025, with annual interest expenditure of approximately €2.9 billion in 2025. These figures illustrate the substantial financial burden that public debt can impose on taxpayers and government finances, particularly in the aftermath of a banking crisis. Nearly two decades later the annual interest cost associated with the bailout was estimated at €650 million in 2025 alone.
Analysing the Boom-Bust-Bailout Cycle that Places Nations in Debt
"There are two ways to conquer and enslave a nation. One is by the sword. The other is by debt." - U.S. President John Adams
The banking system can and does control the availability of credit via expansion or contraction of debt-money loans. Commercial banks play a central role in the creation and allocation of credit within the modern monetary system. During periods of economic optimism, low interest rates, rising asset prices and competition for lending business can encourage banks to expand credit rapidly.
As borrowing increases, additional purchasing power can fuel rising property prices and other asset-price bubbles. Higher asset valuations may then encourage further borrowing, creating a self-reinforcing cycle of credit expansion and increasing financial exposure.
However, when economic conditions deteriorate, asset prices decline or borrowers become unable to service their debts, banks may restrict new lending and attempt to reduce their exposure to risk. The resulting contraction in credit availability can intensify economic downturns, contribute to business failures and increase defaults.
These processes can form part of broader economic and financial cycles. Their severity is influenced by monetary policy, financial regulation, institutional incentives, external shocks and the structure of the banking system.
Where the failure of major financial institutions threatens wider economic stability, governments may subsequently intervene to prevent systemic collapse, potentially transferring substantial private financial losses onto the public balance sheet.
Although such measures are generally justified as necessary to protect financial stability, they can result in substantial public liabilities arising from losses initially incurred within the private banking sector. Critics claim these measures to 'save the nation' are intentionally orcestrated (the bank profits were private, but now the bank losses are socialised i.e., the banks are kept alive by governments, paid from public funds).
Austerity and government spending cuts and tax rises occur to fund the bailout at the expense of the people. This leads to reduced household disposable income, which leads to increased defaults on loans, recession, increased bailout costs, and the cycle continues.
The government may also seek extra funds (debt-money created from nothing) from an organisation, such as the IMF, in order to finance the bailouts, thereby placing the country into yet more national debt and subject to the conditionalities of that loan. Conditionalities often include austerity measures and placing national assets up for sale at a low price if the interest payments on the national debt are not made. To bailout private banks and bond holders the government is in effect mortgaging the future income of the people of the nation - making them pay for losses of private banks.
When the availability of credit is contracted/reduced by the banking system the money supply shrinks, the availability of money to repay loans plus interest is reduced, foreclosures begin to occur and the economy may start to shrink rather than grow. This expansion and contraction of credit is known as the business cycle.
"The fact that the necessary growth can be achieved only by increasing the total level of debt makes the economy heavily dependent on confidence... The economy therefore constantly moves between boom and bust; it is systemically unstable." - John Joplin and Roy Madron, authors of 'Gaian Democracies' iii
"The bankrupt country must borrow from international banks and the IMF, which impose a condition of debt relief that the national government may not issue its own money. If the government tries to protect its resources or its banks by nationalizing them for the benefit of its own citizens, it is branded communist, socialist or terrorist and is replaced by one that is friendlier to free enterprise." - E.H. Brown, Author of the book 'The Web of Debt'
Writing in Chronicles magazine in his article Wall Street Imperialism in March 1998, author Bob Djurdjevic argued that foreign lending, financial crises and IMF bailout conditions could facilitate the transfer of national assets and resources into the hands of powerful international financial. Djurdjevic associates these cycles, which have been experienced by many countries, to what he calls the Wall Street dominated New World Order terrorists:
"The Wall Street dominated New World Order (NWO) Empire is being built by colonizing other countries with foreign loans or investments... [when the nation is firmly on the hook] the NWO financial terrorists pull the plug, leaving the unsuspecting victim high and dry. And begging to be rescued. In comes the International Monetary Fund (IMF). Its bailout recipes - privatisation, trade, liberalization and other austerity reforms - amount to seizing the target countries' natural resources, and turning them over to the NWO elites." - Bob Djurdjevic, Chronicles Journal iv
Crirtics claim that a private-banking cartel or monopoly on credit has been able to drive nations into bankruptcy and bailout using this Problem, Reaction, Solution approach or Hegelian Dialectic. The process can be summarised as follows:
- Credit expansion and financial risk
- Financial crisis and government intervention: When a credit-driven boom collapses, major banks may experience substantial losses, liquidity shortages or insolvency. Governments and central banks may intervene to stabilise the financial system through guarantees, emergency lending, recapitalisation or other measures.
- The solution stage. International financiers, such as the IMF, come to the rescue as the saviour with a loan, the government accepts the loan (which critics assert could be the bailout money that the country has already been conned into paying to the bankers but returns with shark loan rates attached) and the country is then under full banker ownership.
- Transfer of financial burdens: The fiscal consequences of banking rescues may increase public debt, debt-servicing costs and pressure on government finances. Depending on the policy response, these burdens can contribute to public spending reductions, higher taxation, asset disposals or prolonged fiscal adjustment.
- After this, taxes are raised in an attempt to pay off loans. The nation's resources and services maybe captured if they were pledged as collateral on the loan, and the nation becomes in essence economically captured.
The process reveals a fundamental structural problem within the modern financial system. Commercial banks can generate substantial profits through credit expansion, yet when excessive lending contributes to systemic financial instability, governments may intervene to "protect the wider economy", thereby transferring significant financial risks and losses onto the public sector.
The resulting arrangement raises serious questions about financial accountability, moral hazard and the distribution of economic power. It also creates a situation in which private financial institutions may benefit from substantial public support while households, businesses and taxpayers bear much of the economic burden of the ensuing crisis.
The fundamental question is why the consequences of excessive private financial risk-taking should be borne, in significant part, by the wider population, particularly where the institutions responsible for those risks previously enjoyed substantial profits.
The 2008 Banking Crises in Europe: Comparing Ireland's Situation with the Icelandic Solution
The flaws of the monetary system became apparent to many millions of people in 2008 when the so-called banking crises hit in the U.S. and in Europe, yet the system did not change. In Ireland, the debts of the private banks were the controversially guaranteed by the Irish government, thereby placing the debt burdens onto the Irish citizens. According to a poll by the Irish Independent in 2010 a substantial majority of the Irish people wanted the State to default on debts to bondholders v.
The findings of Ireland's parliamentary Banking Inquiry, published in 2016 vi provide substantial evidence of the institutional failures underlying the crisis. The inquiry concluded that decisions by bank executives, management and advisers to pursue risky business practices, combined with inadequate regulation and failures of government oversight, contributed directly to the collapse of the Irish banking system.
The inquiry also identified excessive dependence on short-term wholesale funding, aggressive property lending, inadequate risk management and a regulatory environment that failed to respond effectively to accumulating financial dangers. Significantly, it found that the European Central Bank exerted undue pressure on the Irish Government during its entry into the 2010 bailout programme, while opposing burden-sharing with bank bondholders vii.
These official findings raise serious questions about the accountability of financial institutions, regulators and European monetary authorities, particularly given the substantial costs ultimately borne by the Irish public.
Furthermore, as I noted in a blog in 2010 viii the people of Ireland did not agree to the use of billions of their monies being used to bail out privately owned banks. There was no national referendum on the issue. The bailout of the private banks by the Irish government prompted much public anger, yet, the mainstream media in Ireland appeared to be generally aligned with the government narrative. A number of commentators and bloggers had criticised the government's bailout plans to no avail. For example, the following is an extract from an article titled "We must face down the jackals who control the international banking system to save our nation and protect our children's future" by Robert Pye, a former Irish Department of Finance Analyst:
"THERE IS considerable truth in the view that Ireland is no longer a sovereign state but an impoverished suburb of Brussels. Four million people are mired deep in a collective debt that is not of their own making... They call us PIIGS (Portugal, Ireland, Italy, Greece and Spain) because that is what you do with a pig: tie him upside down, slit his throat and drain him dry. Well, I for one reject this disgusting epithet... Unless we take a stand and defend our sovereignty, our integrity and our children, we will be destroyed as a nation." ix
Richard Douthwaite (1942 - 2011) an economist and writer, wrote in an article titled "Bailout talks: four truths Ireland can't ignore" x:
"If Ireland has to pay interest on the loans being negotiated at a rate which exceeds the rate at which the economy grows over the next few years, it will make the country's situation worse, not better... The ECB bears a large share of the responsibility for the regulatory failure... Ireland doesn't have to take anything that is offered... the Irish government can simply...issue itself with the new currency on a debt-free basis so that it no longer needed to borrow to cover its budget deficit... Ireland has no alternative but to renege on the [bank] guarantees and to build itself a future within the EU but outside the eurozone."
An article on broadsheet.ie in 2010 titled "The Senior Bondholders: An Analysis" xi listed the identity of the bondholders that were benefitting from the Irish tax-payer funded government bailout of privately owned insolvent banks. Many of the bondholders were privately held banks "mostly" owned by extremely wealthy individuals. An extract from the article is as follow:
"SO.... on one side we have Ireland whose bond holders, its people, have between them a total GDP wealth of 0.207 trillion euros. Who are being FORCED, against their will, to pay Anglo Irish bank's debts to its bond holders, who between them hold 20.8 Trillion euros. The people of Ireland are paying to, and protecting the wealth and power of, people who have 100 times more wealth!... So who are they ? Well many of the bond holders are privately held banks, which list their activities as asset management for off-shore, non-resident and high value individuals."
In a November 2010 article xii author and blogger Charles Hugh Smith summarised the situation as follows:
"When a nation such as Ireland is running a State deficit equal to 32% of GDP, austerity cannot generate the stupendous surpluses needed to make good the vast sums which are already lost... Ireland, and indeed the world, will survive if all the vampire banks are liquidated... the citizens... have been yoked to save their"betters."Ireland, please drive a stake through the heart of the vampire banks which have the world by the throat. By defaulting, you would be doing the world (and your own nation) an immense favor."
The contrasting responses of Iceland and Ireland to the 2008 banking crisis are particularly revealing. The Icelandic solution involved repudiation of certain private banking liabilities. Private banks were allowed to fail, while social security measures for the poor and indebted were increased. The UK even invoked anti-terrorism legislation against Icelandic banking assets in an attempt to secure repayment of claims against its failed banks. The Irish government, on the other hand, guaranteed private bank debts and, in doing so, subjected taxpayers to years of payments for debts that had not been incurred on their behalf or for their benefit. This amounted to a form of theft i.e. transferring the financial burden of private banking failures onto the public and future generations. Iceland subsequently recovered more rapidly than Ireland in several important respects, demonstrating that alternative approaches to banking crises were possible xiii.
Further Analysis: Who Owns and Controls the Global Economy?
The consequences of the debt-money system extend beyond banking crises and government bailouts. An equally important question concerns who ultimately owns and controls the major financial institutions and corporations that dominate the global economy.
In an earlier article, first published in February 2025, I examined the landmark Swiss research identifying a highly interconnected network or super-entity of 147 corporations, predominantly financial institutions, exercising substantial control over the global corporate economy.
In a forthcoming follow-up article, I revisit and expand upon this earlier analysis, examining the concentration of corporate ownership, the interconnected nature of major financial institutions, and the influence exercised by asset management companies such as BlackRock through extensive shareholdings and corporate voting rights.
Notes
i Source: feasta.org
ii Sources: irishtimes.com
In August 2020 Ireland's total national debt was €235,688,965,150 (~€235 billion).
iii Available at gaiandemocracy.net
iv Source: chroniclesmagazine.org
v Source: independent.ie
vi Source: inquiries.oireachtas.ie
vii Sources: inquiries.oireachtas.ie
viii Source: "Ireland say NO to any bailout by a foreign private banking cartel" - Mark Keenan sustainableireland.blogspot.com
ix Robert Pye, "Stop Brussels elite from ransacking our country," The Irish Times, 6 May 2011.
x Source: passivehouseplus.ie
xi Source: broadsheet.ie
xii The article is available at: oftwominds.com Read more at: businessinsider.com
xiii Source: wiki.mises.org